Karachi – September 30, 2025: Pakistan’s leading textile manufacturer, Gul Ahmed Textile Mills Limited (GATM), has announced the closure of its export apparel business after years of financial strain and mounting operational challenges.
In a notice to the Pakistan Stock Exchange (PSX), the company stated that its board of directors approved the decision during a meeting held on September 29, 2025. The move comes after a strategic review that highlighted continued losses in the export apparel segment.
According to the company, the export unit has been struggling with rising input costs, especially nominated fabrics, along with higher energy tariffs, policy-driven tax burdens, and a volatile exchange rate that has reduced competitiveness in global markets. Intense competition from regional textile exporters has further squeezed margins.
By shutting down this business line, Gul Ahmed expects to reduce borrowing levels, improve cash flows, and strengthen its focus on profitable areas such as home textiles, spinning, and weaving, which remain operational.
Gul Ahmed, a household name in Pakistan, traces its roots back to the early 1900s as a textile trader and began manufacturing under GATM in 1953. Listed on the PSX since 1955, the company also runs one of the country’s largest retail networks, with more than 40 outlets offering fashion, apparel, and home accessories.
The closure of its export apparel division marks a major restructuring step for the textile giant as it navigates Pakistan’s challenging economic and industrial landscape.
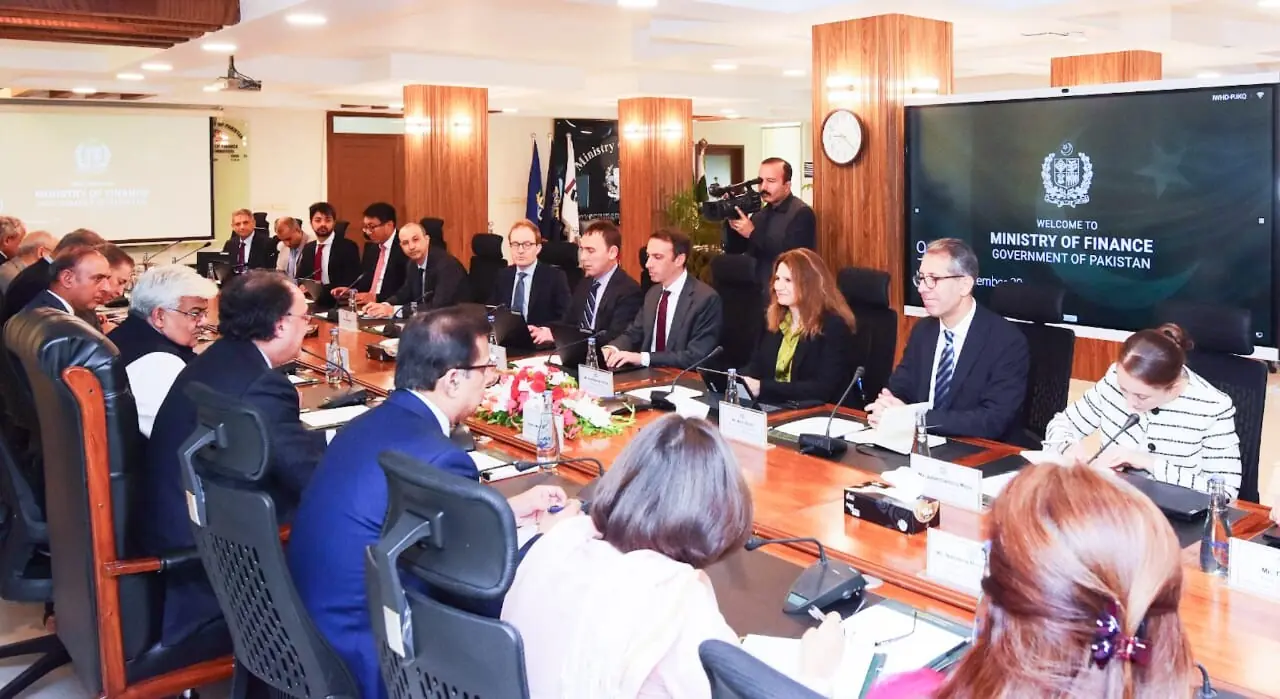
Pakistan’s Ministry of Finance commenced high-level discussions with the International Monetary Fund (IMF) in Islamabad to review the country’s fiscal performance and outline the government’s economic roadmap. The meetings, chaired by Finance Minister Muhammad Aurangzeb, brought together key officials including Finance Secretary Imdadullah Bosal, State Bank of Pakistan (SBP) Governor Jameel Ahmed, and Federal Board of Revenue (FBR) Chairman Rashid Mahmood Langrial.
The discussions form part of a broader review under Pakistan’s $7 billion Extended Fund Facility (EFF) and an additional $1.4 billion loan approved earlier this year to support climate resilience initiatives. The IMF delegation is tasked with assessing Pakistan’s progress on key fiscal targets, including revenue generation, governance reforms, and anti-corruption measures. Officials from the Ministry of Finance emphasized the need for transparency and detailed reporting to ensure that the ongoing economic programs remain on track.
“The talks are essential for both sides to review Pakistan’s fiscal health and evaluate progress under the EFF program,” said a senior official in the Ministry of Finance. “This engagement will help us align our policies with IMF guidelines while ensuring the government’s priorities for economic growth and fiscal stability are maintained.”
Key areas of focus during the meetings include strengthening the tax collection framework, improving governance across federal institutions, and monitoring measures related to anti-money laundering and anti-corruption. The IMF delegation has also requested detailed updates on the implementation of structural reforms, particularly those designed to enhance fiscal discipline and ensure efficient utilization of financial resources.
Experts say these discussions are crucial not only for the continuation of IMF financial support but also for Pakistan’s broader economic stability. “The IMF reviews provide both oversight and technical guidance that can help Pakistan address revenue shortfalls, improve fiscal management, and attract foreign investment,” said an economic analyst based in Islamabad. “These talks will set the tone for future disbursements and the government’s ability to manage debt and budgetary priorities.”
The outcome of the IMF talks will be pivotal in determining the release of subsequent tranches under the bailout program. These funds are vital for Pakistan as the country navigates economic challenges, including fiscal deficits, inflationary pressures, and external debt obligations. Analysts note that timely implementation of agreed measures can bolster investor confidence and strengthen Pakistan’s macroeconomic position.
Apart from fiscal reforms, the IMF discussions are also expected to cover climate-related financing, following the $1.4 billion loan approved to support Pakistan’s climate resilience programs. The focus will be on ensuring that financial flows are efficiently utilized for projects addressing climate risks, sustainable development, and disaster management.
While the government has expressed optimism regarding the discussions, the IMF has reiterated the importance of strict compliance with agreed reforms, regular monitoring, and transparent reporting mechanisms. Both sides have committed to continued dialogue to ensure that fiscal targets are met and economic stability is maintained.
With these talks underway, Pakistan aims to reinforce fiscal discipline, enhance governance structures, and secure critical funding necessary for sustaining economic growth. The successful conclusion of the discussions is expected to pave the way for continued financial support from the IMF and strengthen Pakistan’s prospects for macroeconomic stability in the coming years.
Reko Diq Project: ECC Review Boosts Pakistan Mining and Copper-Gold Output
Pakistan’s Economic Coordination Committee (ECC) has intensified scrutiny on the Reko Diq copper-gold project, highlighting its growing importance for the country’s mining sector and overall economic development. The ECC has requested a detailed execution plan for railway agreements and comprehensive financing arrangements, with a target completion date of March 30, 2026.
The Ministry of Railways emphasized that the Reko Diq project is classified as a “qualified investment” under the Foreign Investment (Promotion and Protection) Act 2022. A dedicated railway track will be constructed to transport copper-gold concentrate from the mines in Balochistan to export terminals over 1,350 kilometers. This crucial infrastructure will ensure efficient bulk transport and support large-scale mining operations, reinforcing Pakistan’s position in the global mining industry.
In addition, the ECC approved revised financing arrangements, which focus on environmental sustainability, health and safety, and community development. Major international lenders and creditors are directly arranging the financing, reflecting strong investor confidence in the project.
Global financial institutions have also shown significant commitment. The International Finance Corporation (IFC) has contributed $400 million in subordinated loans, raising its total investment to $700 million. Meanwhile, the Asian Development Bank (ADB) approved a $300 million loan, marking its first investment in mining projects in Pakistan in over four decades. These financial commitments highlight the strategic value of the Reko Diq project.
The Reko Diq project, a joint venture between Barrick Gold, the federal government, and the Balochistan provincial government, is expected to become one of the world’s largest copper-gold mines. With an estimated $74 billion in free cash flow over its 37-year lifespan, production is slated to begin by 2028. The first phase, costing $5.5 billion, aims to produce 200,000 tons of copper annually, with plans to expand output in subsequent phases.
With the ECC overseeing the project’s progress, successful implementation of infrastructure and financing plans will be pivotal in achieving Pakistan’s economic growth goals, strengthening the mining sector, and boosting foreign investment in the country.
Pakistani rupee faces forex pressure as economy struggles with trade deficit and inflation
Karachi – Pakistan’s economy remains under tight watch as the Pakistani rupee faces volatility in the foreign exchange market. Importers and exporters alike are struggling to cope with the ongoing instability, while analysts caution that without immediate corrective measures, the economic crisis in Pakistan could worsen.
In recent weeks, the rupee has traded in a fluctuating band, reflecting pressure on Pakistan’s forex reserves and uncertainty in international trade. Importers are voicing concerns over rising import costs of raw materials and finished goods, driven largely by rupee depreciation and higher international oil prices. At the same time, exporters are highlighting inconsistent trade policies in Pakistan, which are making it difficult to maintain competitiveness in global markets.
Experts believe that Pakistan’s persistent trade deficit continues to fuel the crisis. The country’s imports remain significantly higher than its exports, increasing pressure on the current account. Unless the government introduces effective reforms in the export sector and reduces dependency on costly imports, the rupee is likely to remain under stress.
Meanwhile, inflation in Pakistan continues to bite households and businesses. Prices of essential commodities such as wheat, sugar, and cooking oil remain high, eroding the purchasing power of ordinary citizens. Small and medium enterprises (SMEs) are also reporting higher operational costs, raising fears of reduced productivity and potential layoffs.
Financial analysts suggest that the government should focus on stabilizing the rupee through tighter fiscal discipline, ensuring consistency in trade and tax policies, and encouraging foreign direct investment (FDI) in Pakistan to boost reserves. The State Bank of Pakistan (SBP) has already hinted at possible interventions, but market watchers say monetary measures alone may not be sufficient without broader economic reforms.
Despite challenges, some economists see opportunities. They argue that if Pakistan invests in value-added exports such as textiles, information technology (IT), and agriculture-based industries, it could improve foreign exchange earnings and reduce pressure on the currency.
For now, uncertainty dominates the financial landscape. With global economic headwinds, fluctuating oil prices, and domestic political challenges, the road to economic stability in Pakistan remains bumpy. All eyes are on Islamabad to see whether upcoming policy decisions will bring much-needed relief—or add further strain to an already fragile situation.
Raising teenagers can be exciting, but it often comes with rising costs. From school supplies to clothing, gadgets, and entertainment, parents usually feel the financial pressure. The good news is that with some smart strategies, you can reduce teen expenses without compromising on your child’s happiness and growth. Here are some practical family money hacks and parenting tips for teenagers that work.
1. Smart Education & Learning Choices
One of the biggest costs for kids is education. Instead of buying brand-new textbooks, explore second-hand books or digital versions. Encourage your children to use online learning platforms like Khan Academy and YouTube for free courses. Visiting libraries is another budget-friendly way to promote reading and learning. These steps help in budgeting for kids while still giving them quality education.
2. Affordable Clothing & Fashion
Teenagers love fashion, but it doesn’t have to drain your wallet. Shop during off-season sales where prices are heavily discounted. Encourage clothing swaps with friends or cousins, and invest in durable basics instead of constantly buying trendy outfits. Teaching kids about smart spending for teens helps them understand the value of money.
3. Food & Snacks on a Budget
Eating out and buying daily snacks from school canteen adds up quickly. Packing homemade lunches and snacks saves money and is healthier. Buying items like biscuits, chips, and juices in bulk and dividing them into portions is another simple way to save money with teens. Replacing junk food with fruits or homemade options also reduces costs in the long run.
4. Managing Gadgets & Entertainment
Gadgets and subscriptions are another expense category for teens. Avoid upgrading phones every year and instead use devices until they truly need replacing. Opt for family Netflix or Spotify plans instead of individual ones. Encourage hobbies such as reading, drawing, or sports that are free and fun. These small steps can greatly reduce teen expenses.
5. Transport & Social Life
If possible, encourage walking or cycling to school or nearby places. Carpooling with neighbors or using school transport also helps. For social gatherings, suggest simple hangouts at home instead of expensive restaurants. Setting a monthly pocket money budget teaches children responsibility while keeping costs under control.
6. Building Money Habits in Teens
Perhaps the most valuable step is involving teenagers in family budgeting discussions. This helps them understand real-life finances and encourages them to make wise spending choices. If possible, motivate them to explore part-time work or freelancing to earn extra income. Teaching them to save before spending builds habits that last a lifetime.
Final Thoughts
Raising kids doesn’t have to mean draining your bank account. By applying these parenting budget hacks, you can easily reduce expenses for kids aged 13 and above while still ensuring they enjoy their teenage years. Remember, teaching financial responsibility today means building independent and money-smart adults tomorrow.
Starting an online business is one of the best ways to earn money, achieve independence, and reach a global audience without heavy startup costs. In today’s digital world, almost anyone can build an online business with the right idea and strategy. Here’s a step-by-step guide to help you get started.
1. Choose Your Business Idea
The first step is identifying what you want to sell. Your business could be based on products, services, or digital goods. For example:
Choose an idea that matches your skills and interests while solving a problem for your target audience.
2. Decide Your Business Model
Different models suit different entrepreneurs:
E-commerce stores using platforms like Shopify, WooCommerce, or Daraz.
Freelancing on websites like Fiverr and Upwork.
Affiliate marketing, where you earn by promoting other people’s products.
Content creation (YouTube, blogging, or podcasts).
3. Build Your Online Presence
A strong online presence builds trust and credibility. Start with a professional website and social media pages. Tools like WordPress, Wix, or Shopify make it easy to launch your store without coding. Use social platforms like Instagram, Facebook, and TikTok to showcase your business and connect with customers.
4. Set Up Payment and Delivery
Make it easy for customers to pay you. Depending on your country, integrate payment gateways like PayPal, Stripe, or local bank transfers. If you’re selling physical products, plan your shipping and delivery process. For services or digital products, set up automatic delivery systems to save time.
5. Market Your Business
Marketing is key to growth. Use social media marketing, email campaigns, and even paid ads to attract customers. Collaborate with influencers or run special promotions to build awareness. Remember, consistency is more important than perfection.
Final Thoughts
Starting an online business doesn’t require huge investment—it requires commitment, creativity, and patience. Begin with a simple idea, test it, and improve as you go. With the right plan and persistence, you can turn your online business into a long-term source of income and financial freedom.
Managing money wisely has become a life skill everyone needs in today’s fast-changing economy. Whether you are a student, young professional, or a family head, creating a personal finance plan helps you stay secure, achieve your goals, and avoid unnecessary debt.
What is Personal Finance?
Personal finance is the management of your income, expenses, savings, and investments to ensure financial stability and long-term growth. It’s about making money work for you—not the other way around.
Steps to Create a Personal Finance Plan
1. Assess Your Current Situation
Write down your income sources, monthly expenses, and debts. 👉 Example: If your monthly salary is Rs. 100,000, track how much goes into rent, groceries, transport, and savings.
2. Set Clear Goals
Short-term: Build an emergency fund.
Medium-term: Save for a car or house down payment.
Long-term: Retirement or children’s education.
👉 Example: A professional saving Rs. 20,000 per month can build an emergency fund of Rs. 240,000 in just one year.
3. Build a Budget
Follow the 50/30/20 rule:
50% for needs (rent, food, bills)
30% for wants (shopping, travel)
20% for savings & investments
4. Manage Debt Smartly
Clear high-interest loans first (credit cards, personal loans). This reduces financial stress.
5. Save & Invest Consistently
Open a savings account or invest in mutual funds, stocks, or retirement accounts.
Even small investments, if consistent, grow significantly due to compound interest.
👉 Example: Investing just Rs. 10,000 per month with a 10% return can grow to Rs. 20 lakh+ in 10 years.
6. Protect Yourself with Insurance
Health, life, and property insurance prevent sudden financial shocks.
Learn from Experts & Organizations
To create a strong personal finance strategy, it helps to follow expert advice:
Creating a personal finance plan is not just about cutting expenses—it’s about building a secure future. Start small, stay consistent, and learn from experts. The earlier you start, the greater your financial freedom.