The US Dollar is trading at around Rs. 278.5–278.7 in Pakistan’s open market and Rs. 277.55–278.05 in the interbank market today, 16 August 2026. Here’s the full breakdown across major currencies and what moves these rates day to day.
Today’s open market rates
Currency
Buying (PKR)
Selling (PKR)
US Dollar (USD)
278.50
278.70
Euro (EUR)
320.05
325.55
British Pound (GBP)
374.89
380.84
Saudi Riyal (SAR)
74.05
74.70
UAE Dirham (AED)
76.15
77.15
Today’s interbank rate (USD)
Rate type
Value (PKR)
Bank buying (TT Clean)
277.55
Bank selling (TT & OD)
278.05
Open market vs interbank: what’s the difference?
Interbank rate is what banks use to trade currency among themselves and with the State Bank of Pakistan — the closest thing to an “official” benchmark rate.
Open market rate is what you’ll actually get at a currency exchange counter or money changer, and typically runs slightly higher than the interbank rate for buying dollars.
The gap between the two widens when demand for dollars is high relative to supply — a useful signal of currency market pressure.
Why the exchange rate matters for Pakistan
The dollar-rupee rate feeds directly into import costs, including the energy imports that determine petrol and diesel prices and the international gold benchmark behind the gold rate in Pakistan. A weaker rupee raises the rupee cost of every dollar-denominated import, while remittances sent home by overseas Pakistani workers — including the growing flow from Gulf employment — become worth more in rupee terms when the dollar strengthens.
What moves the rate day to day
Remittance inflows. Higher inflows from overseas workers ease dollar demand and support the rupee.
Import bills. Energy and commodity import payments are among the largest sources of dollar demand.
SBP reserves and policy. State Bank interventions and reserve levels influence how much the rate is allowed to move.
Global dollar strength. Broad-based dollar strength or weakness against other currencies also spills into the PKR rate.
Frequently asked questions
What is the dollar rate in Pakistan today?
As of 16 August 2026, the open market rate is around Rs. 278.5 (buying) to Rs. 278.7 (selling), while the interbank rate is Rs. 277.55 to Rs. 278.05.
Why is the open market dollar rate higher than the interbank rate?
Open market rates reflect actual retail supply and demand at exchange counters, which typically run slightly above the interbank benchmark used for bank-to-bank trading.
Where can I check the live exchange rate?
The State Bank of Pakistan publishes official interbank rates, while licensed exchange companies display current open market buying and selling rates — both change throughout the trading day, so treat any single snapshot as indicative rather than final.
Rates as of 16 August 2026, sourced from open market and interbank currency data. Exchange rates change minute to minute — treat these figures as indicative and verify current rates with your bank or exchange company before any transaction.
Two prize bond draws are scheduled for 17 August 2026: the Rs. 1,500 draw (#107) in Faisalabad and the Rs. 100 draw (#55) in Multan. Here’s the full schedule, prize amounts, and exactly how to check your bond numbers once results are announced.
17 August 2026 draw details
Denomination
Draw #
City
Date
Rs. 1,500
#107
Faisalabad
17 August 2026
Rs. 100
#55
Multan
17 August 2026
Rs. 1,500 prize bond: prize structure
Prize
Amount
Number of winners
1st Prize
Rs. 3,000,000
1
2nd Prize
Rs. 1,000,000
3
3rd Prize
Rs. 18,500
1,696
Rs. 100 prize bond: prize structure
Prize
Amount
Number of winners
1st Prize
Rs. 700,000
1
2nd Prize
Rs. 200,000
3
3rd Prize
Rs. 1,000
1,199
How to check your prize bond result
Note your bond details. Have your bond denomination (Rs. 100 or Rs. 1,500) and full serial number(s) ready.
Visit the official source. Results are published by the Central Directorate of National Savings (CDNS) at savings.gov.pk, and are also mirrored by the State Bank of Pakistan.
Select the correct draw. Choose the denomination and the specific draw number (#107 for Rs. 1,500, #55 for Rs. 100) rather than searching by date alone.
Match your number(s). Compare your bond’s serial number against the published winning number lists for 1st, 2nd and 3rd prizes.
Verify before acting. If you find a match, confirm it against the official CDNS gazette notification before visiting a bank to claim — unofficial aggregator sites occasionally contain transcription errors.
How the prize bond draw schedule works
Each prize bond denomination is drawn four times a year, on a fixed quarterly cycle, rotating through major cities including Karachi, Lahore, Islamabad, Rawalpindi, Peshawar, Quetta, Multan, Faisalabad, Hyderabad and Sialkot. Across all eight denominations (Rs. 100, 200, 750, 1,500, 7,500, 15,000, 25,000 and 40,000), roughly 36 draws are held every year, meaning there is a prize bond draw of some denomination almost every month.
The Rs. 1,500 and Rs. 100 denominations both follow a February–May–August–November quarterly pattern, which is why they land on the same date this cycle. The previous Rs. 1,500 draw (#106) was held in Sialkot on 15 May 2026, and the next Rs. 100 draw (#56) after this one is scheduled for 16 November 2026 in Faisalabad.
Frequently asked questions
What is the 1st prize amount for the Rs. 1,500 prize bond?
Rs. 3,000,000 (30 lakh rupees), awarded to a single winning bond number in each draw.
Where can I check the official prize bond result?
The Central Directorate of National Savings publishes official results at savings.gov.pk. Always cross-check any result you see on a private aggregator site against this official source before making a claim.
How often are prize bond draws held?
Each denomination is drawn quarterly (four times a year), with the draw city rotating each time. Across all eight denominations combined, there are roughly 36 draws a year.
Draw numbers, cities and prize amounts as per the published 2026 National Savings draw schedule, current as of 16 August 2026. Always verify results against the official Central Directorate of National Savings (CDNS) website before making any financial claim.
Pakistan’s government has raised the petroleum dealers’ margin to Rs9.98 per litre on petrol and high-speed diesel, an increase of Rs1.34 announced on 14 August 2026 — a move that headed off a nationwide pump strike called for the very next day.
The decision came from the Economic Coordination Committee (ECC), chaired by Finance Minister Senator Muhammad Aurangzeb, hours before the All Pakistan Petroleum Dealers Association’s strike deadline. Here’s what changed, why, and what it means for the price you pay at the pump.
What actually changed
Item
Before
After
Dealers’ margin (petrol & diesel)
Rs8.64/litre
Rs9.98/litre
Increase
Rs1.34 per litre
Approved by
ECC, 14 August 2026
The dealers’ margin is the fixed cut retail outlets earn on every litre sold, separate from the ex-refinery price, oil marketing company (OMC) margin, petroleum levy and sales tax that together make up the pump price. Raising it does not automatically mean petrol gets Rs1.34 more expensive for consumers — that depends on whether the government absorbs the cost elsewhere or lets it flow through at the next fortnightly price review.
Why the increase happened now
The All Pakistan Petroleum Dealers Association had threatened to shut down fuel stations countrywide from 15 August 2026, arguing their margin had failed to keep pace with rising operating costs — wages, electricity, compliance and transport — while remaining fixed for an extended period. A nationwide pump closure would have hit commuters, freight and emergency services within hours, so the ECC moved a day ahead of the deadline.
The Vice Chairman of the All Pakistan Petrol Pump Owners Association confirmed the increase and thanked Prime Minister Shehbaz Sharif and Petroleum Minister Ali Pervaiz Malik for resolving the dispute before the strike took effect.
Who this affects
Petrol pump owners get a higher per-litre margin immediately, easing pressure that had built up over months of flat or falling retail margins relative to cost.
Consumers may or may not see the increase reflected at the pump — it depends on the next OGRA price notification and how much of the levy/margin adjustment the government chooses to pass on versus absorb.
Transporters and industry that depend on uninterrupted diesel supply avoided a one-day (or longer) countrywide disruption that a strike would have caused.
How this fits the bigger fuel-pricing picture
Pakistan’s pump price is built from several moving pieces: the international product price (linked to Brent crude and refining margins), the rupee-dollar exchange rate, the petroleum levy, general sales tax, the OMC margin and the dealers’ margin. A change in any one of these can move the retail price independently of what is happening to crude oil internationally — which is also why petrol and diesel prices sometimes move in opposite directions on the same review date, as seen with recent Strait of Hormuz-driven price swings.
Margin increases like this one are a recurring flashpoint. Dealers argue their cut has not kept up with inflation; consumer groups argue every rupee added anywhere in the chain eventually reaches the pump. Both are broadly correct — the margin is a real cost element, but it is a small share of the roughly Rs300+ per litre retail price compared with the international product cost and taxes.
What to watch next
The next OGRA price notification (fortnightly) — this will show whether the margin hike is absorbed by the government or passed through to consumers.
OMC margin talks — oil marketing companies have periodically sought similar increases; a parallel demand could follow.
Petroleum levy adjustments — the government has room to offset dealer-margin costs by trimming the levy, or to let both increases stack.
Frequently asked questions
Will petrol prices in Pakistan go up because of this?
Not necessarily right away. The dealers’ margin is one small component of the pump price. Whether the increase shows up in what you pay depends on the next fortnightly OGRA price review and whether the government offsets it through the levy.
What is a petroleum dealers’ margin?
It’s the fixed amount, in rupees per litre, that a fuel retailer (petrol pump) earns on every litre sold — set by the government and reviewed periodically, separate from the OMC margin, levy and taxes.
Why were dealers threatening a strike?
The All Pakistan Petroleum Dealers Association said their margin had not risen in line with operating costs, and called a nationwide strike for 15 August 2026 to press for an increase — which the ECC granted a day earlier.
Figures and statements sourced from ECC announcements and petroleum-industry reporting as of 15 August 2026. Pump prices change under OGRA’s fortnightly pricing mechanism — check the latest official notification before relying on any figure here.
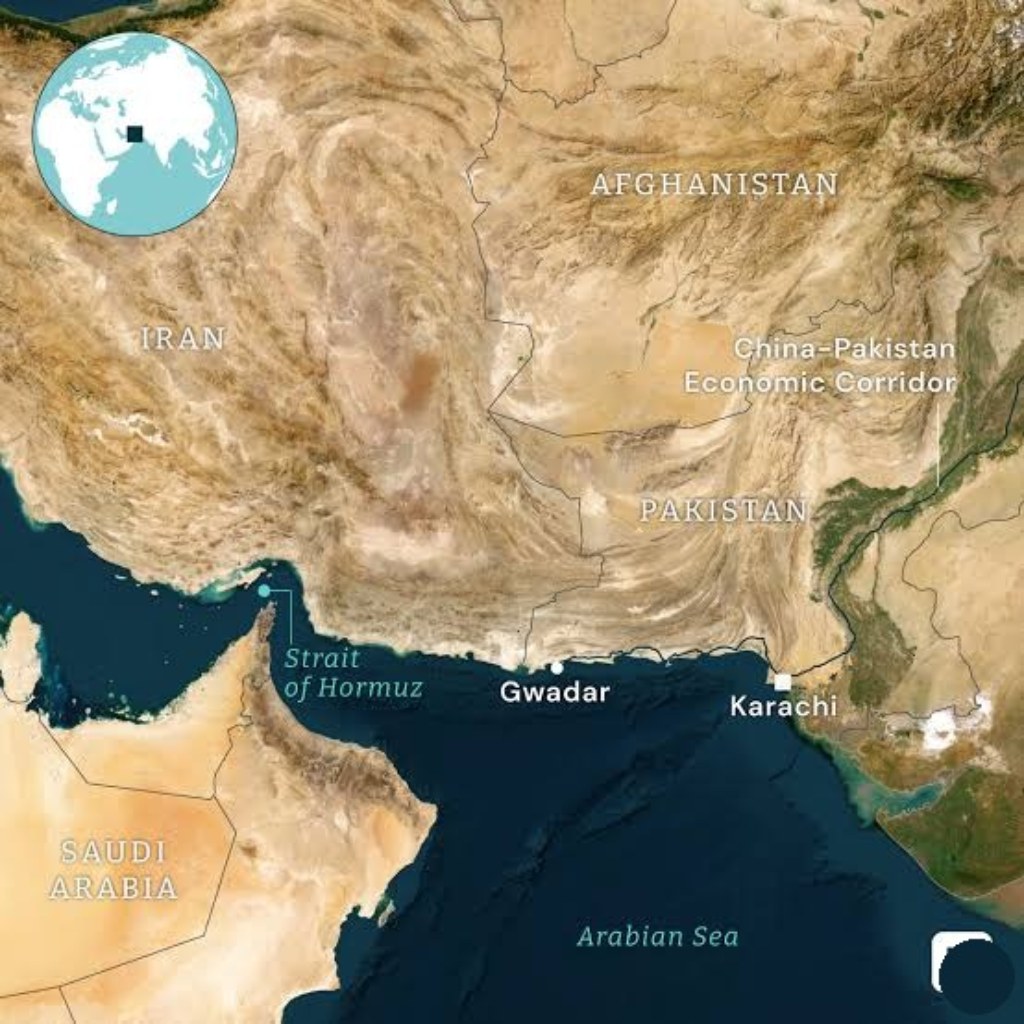
The Strait of Hormuz — the 21-mile-wide channel that normally carries one-fifth of the world’s oil — is effectively closed to commercial traffic. Between 4 and 6 August 2026, just 8 to 15 vessels crossed daily, against roughly 130 transits before the conflict began.
Pakistan imports most of its crude and refined fuel, and a large share of it moves through or near that chokepoint. This article traces the chain from a closed waterway to the price on the pump — and explains why the connection is less direct than it first appears.
Where things stand
Brent crude for October delivery was trading around $84.11 a barrel on 10 August 2026, up about 0.7% on the day and roughly 16% higher than before the US–Israel war on Iran began in late February 2026.
Iran has attached conditions to reopening the strait. Foreign Minister Abbas Araghchi has said Tehran requires the easing of US sanctions and the payment of war reparations, adding that Iran and Oman were close to an understanding but that these conditions must be met first.
The human cost of the disruption is documented: the International Maritime Organization has recorded 64 violent incidents and 17 deaths involving commercial vessels since the war began.
Markets are pricing uncertainty rather than a resolution. As KCM Trade chief analyst Tim Waterer put it, the absence of concrete movement and unresolved questions about how any deal would work in practice keeps “a risk premium in the price.”
Why $84 oil is lower than you might expect
This deserves attention, because it runs against intuition. A fifth of global oil supply losing its main route would, in most historical scenarios, have sent prices well past $120. Brent at $84 reflects several offsetting factors:
Alternative routes exist. Saudi Arabia’s East–West pipeline and the UAE’s Fujairah pipeline can move some volumes to Red Sea and Gulf of Oman terminals, bypassing Hormuz — though at reduced capacity.
Strategic reserves. Consumer countries have released stocks to cushion the shortfall.
Non-OPEC supply. US, Brazilian and Guyanese production has grown substantially over the past decade, diluting the Gulf’s share of marginal supply.
Demand destruction. High prices and slower global growth have themselves reduced consumption.
The implication for Pakistan is double-edged. The buffers have worked so far, but they are finite. Reserves deplete and bypass pipelines are already near capacity. If the closure extends, the cushion thins.
How this reaches the Pakistani pump
Pakistan now uses a more frequent fuel-pricing mechanism tied to international movements. Recent OGRA-notified rates, effective 13 August 2026:
Fuel
Price (PKR/litre)
Change
Petrol
324.98
−0.94
High-speed diesel
382.79
+0.54
Kerosene
291.45
—
Light diesel oil
248.72
—
Notice the direction: petrol fell slightly while diesel rose, on a day when Brent was climbing. Four things sit between the crude price and your receipt:
Refined product prices, not crude. Pakistan imports finished petrol and diesel. Refining margins move independently of crude, which is why petrol and diesel can diverge on the same day.
The exchange rate. Oil is priced in dollars and sold in rupees. Currency movement can amplify or offset the crude move entirely.
Taxes and levies. Petroleum levy and sales tax are a large share of the retail price, and they are policy variables — the government can absorb or pass on international moves.
Margins. Dealer and oil marketing company margins are regulated and adjusted periodically. The ECC recently approved a Rs1.34 increase in dealers’ margin, which raises the pump price independently of anything happening in the Gulf.
The knock-on effects that matter more than petrol
For most Pakistani households, the fuel price itself is not the largest channel. Three indirect effects hit harder.
Freight and food prices
High-speed diesel powers trucking and agricultural machinery, so diesel increases propagate into food prices across the country. Diesel rising while petrol falls is therefore worse for inflation than the headline suggests. Transport costs have already triggered friction — Pakistani goods transporters began an indefinite strike over fuel prices and taxes.
Energy is Pakistan’s largest import category. A sustained rise widens the import bill, pressures the current account and the rupee, and constrains the State Bank’s room to cut rates — the transmission channel set out in our inflation outlook.
There is one meaningful offset. Gulf employment has held up through the conflict, and remittances — over $4.2 billion in May 2026 alone — help fund the higher import bill.
What to watch next
Daily Hormuz transit counts. A move back toward 130 vessels a day would deflate the risk premium faster than any announcement.
The Oman-mediated track. Araghchi has pointed to it as the live channel.
Tanker insurance rates. War-risk premiums are a real-time market read on whether traders expect escalation.
Not legally closed, but effectively so for commercial shipping. Traffic fell to 8–15 vessels a day in early August 2026 from about 130 before the conflict. A small number of transits continue under elevated risk.
Will petrol prices in Pakistan rise sharply?
That depends on refined product prices, the rupee and government tax decisions — not on crude alone. Recent notifications have shown small moves in both directions. Anyone claiming to know the next figure in advance is guessing.
Does Pakistan get its oil through Hormuz?
A significant share of Pakistan’s crude and refined imports originates from Gulf suppliers whose exports transit or depend on the strait. Pakistan has been broadening its oil import framework, partly to diversify sourcing.
Why did diesel go up while petrol went down?
They are separate products with separate international benchmarks and refining margins. Diesel demand is driven by freight and industry, petrol by private vehicles, and the two markets frequently move apart.
Oil prices, transit data and official statements sourced from Al Jazeera, CNBC, the International Maritime Organization and OGRA notifications as reported. Fuel prices are those effective 13 August 2026 and change under Pakistan’s revised pricing mechanism — check current OGRA notifications before relying on them. Last updated 15 August 2026.
The gold rate in Pakistan is sitting near record territory. On Saturday 15 August 2026, 24-karat gold was quoted at roughly Rs459,900 to Rs464,000 per tola depending on the source, with the international spot price around $4,375–$4,415 per ounce.
That range is not a typo, and understanding why different outlets print different numbers on the same day is the first useful thing to know about buying gold in Pakistan. This explainer covers where the price comes from, why it has risen so far, and what to check before you buy.
Gold rate in Pakistan today: the reference numbers
The recognised domestic benchmark is set by the All Pakistan Sarafa Gems and Jewellers Association (APSGJA), which issues rates during the trading session. Figures reported for 15 August 2026:
Measure
Reported rate (PKR)
24k, per tola
459,936 – 463,936
24k, per 10 grams
394,320 – 397,750
22k, per tola
~425,275
21k, per tola
~405,944
Silver, per tola
~7,111
International spot
$4,375 – $4,415 / ounce
ARY News reported the 24k tola rate at Rs459,936, down Rs500 on the session, attributing the decline to softer international bullion prices “amid continued geopolitical uncertainty.” Pakistan Observer published Rs463,936 for the same day. Both cite APSGJA.
Why published rates disagree — and which to trust
Three ordinary reasons account for almost all of the variation, and none of them involve anyone being wrong:
Timing within the session. Gold trades continuously. A rate captured at market open differs from one captured at midday. Outlets publishing at different hours print different numbers from the same association.
City premiums. Karachi, Lahore, Islamabad, Peshawar and Quetta markets carry small differences driven by local supply, transport and demand.
Bullion price versus shop price. The APSGJA rate is for the metal. What you pay at a jeweller adds making charges (typically a percentage of value or a per-tola fee) plus applicable tax. On jewellery this gap is routinely 5–20% above the quoted bullion rate.
Practical takeaway: treat any published “gold rate today” figure — including this one — as an indicative benchmark, not a transaction price. Confirm the rate with your jeweller at the moment of purchase.
How the Pakistani price is actually built
The domestic rate is not set independently. It is essentially the international spot price translated into rupees, adjusted for local market conditions. The mechanism has two inputs:
The dollar price of gold per ounce on international markets.
The PKR/USD exchange rate.
This is why the local price can rise even on a day when international gold falls: if the rupee weakens by more than gold declines, the rupee price still goes up. It also explains why Pakistani gold prices have set records more frequently than dollar gold prices have — the currency has been doing part of the work.
A spot price above $4,300 an ounce is historically extraordinary. Four forces are driving it.
Geopolitical risk premium
The US–Israel war on Iran, which began in late February 2026, and the effective closure of the Strait of Hormuz to commercial shipping have created sustained safe-haven demand. Gold’s classic function is insurance against exactly this kind of uncertainty, and the premium has not faded because the underlying conflict has not resolved.
Central bank buying
Central banks have been persistent net buyers of gold, diversifying reserves away from concentration in any single currency. This is structural, price-insensitive demand — it does not retreat when prices rise, which removes a natural ceiling.
Real interest rates
Gold pays no yield, so it competes with interest-bearing assets. When inflation-adjusted returns on bonds fall, the opportunity cost of holding gold drops and demand rises. Rate expectations have been the main driver of gold’s shorter-term swings this year.
Currency hedging
In Pakistan specifically, households have long used gold as a store of value against rupee depreciation. That demand is culturally embedded — through wedding purchases in particular — and tends to strengthen precisely when confidence in the currency weakens.
What this means if you are buying
Some practical points, offered as information rather than advice:
Know your karat. 24k is near-pure and priced highest; 22k and 21k contain more alloy and cost less per tola. Jewellery is rarely 24k because pure gold is too soft.
Ask for the breakdown. Request the bullion rate, the making charge and the tax separately. A jeweller who will not itemise is worth questioning.
Check hallmarking. Verify purity certification rather than relying on the seller’s description.
Understand the resale gap. Making charges are generally not recoverable on resale. If you are buying primarily as a store of value rather than to wear, coins and bars carry lower spreads than jewellery.
Volatility runs both ways. This site has reported single-day moves of over Rs10,000 and Rs24,300 per tola in 2026, in both directions. Record highs are not a guarantee of further gains.
FutureSoch is not a financial adviser. Nothing here is a recommendation to buy or sell gold. Consider your own circumstances and, where appropriate, take professional advice.
Frequently asked questions
What is one tola in grams?
One tola equals 11.664 grams. This is why the per-tola figure is always higher than the per-10-gram figure — and a useful cross-check if a quoted rate looks wrong.
Who sets the official gold rate in Pakistan?
The All Pakistan Sarafa Gems and Jewellers Association issues the reference rates that media outlets report. It is an industry body, not a government regulator.
Why is the price in my city different?
Local supply and demand, transport costs and individual jeweller margins all vary. City-level differences of a few thousand rupees per tola are normal.
Can gold prices fall from here?
Yes. Gold fell more than Rs10,000 per tola in June 2026 and dropped Rs24,300 before Eid in March 2026. If the Hormuz situation de-escalates, the geopolitical premium currently supporting prices could unwind quickly.
Rates as reported by the All Pakistan Sarafa Gems and Jewellers Association via ARY News and Pakistan Observer for 15 August 2026. Where sources differ, both figures are shown rather than one being selected. Gold prices change continuously — verify before transacting. Last updated 15 August 2026.
ISLAMABAD: The Economic Coordination Committee (ECC) has approved an increase of Rs1.34 per litre in the dealers’ margin on petrol and diesel, raising the margin from Rs8.64 to Rs9.98 per litre.
The decision was taken at an ECC meeting chaired by Finance Minister Senator Muhammad Aurangzeb.
The increase will apply to both petrol and diesel, according to the decision.
Noman Butt, vice chairman of the All Pakistan Petroleum Pumps Owners Association, welcomed the move and thanked Prime Minister Shehbaz Sharif and the petroleum minister for approving the increase.
Butt said the government had fulfilled a longstanding demand of petrol pump owners by increasing the dealers’ margin by Rs1.34 per litre.
ISLAMABAD: Global oil prices fell as prospects for an extension of the Iran-U.S. ceasefire eased concerns about potential disruptions to crude supplies from the Middle East, while expectations of weaker global oil demand also weighed on the market.
Brent crude futures for October delivery fell $1.29, or about 1.5%, to $87.69 a barrel. U.S. West Texas Intermediate crude declined $1.30, or 1.6%, to $81.97 a barrel, according to market data.
U.S. President Donald Trump has also signaled that consumers could soon see a significant decline in gasoline prices, adding to expectations of lower energy costs.
Analysts said the latest decline was driven largely by concerns over weaker global oil demand in 2026 and reports of rising U.S. crude inventories. Higher inventories generally indicate increased supply availability and can put downward pressure on prices.
Investors, however, remained cautious because of continuing risks linked to the Iran conflict and the Strait of Hormuz, a critical shipping route through which a significant share of global oil supplies passes.
Any disruption to oil shipments through the Strait of Hormuz could sharply reduce global supplies and trigger another surge in crude prices. The geopolitical risks have therefore limited the extent of the recent decline.
According to Reuters, investors are closely watching forecasts for global oil demand, U.S. inventory data and developments surrounding the Iran conflict. Lower demand projections from OPEC and other energy agencies have raised concerns that global oil consumption could remain weaker than previously expected.
Market participants are also monitoring developments in the Middle East as any deterioration in the security situation could quickly reverse the recent decline in oil prices.
Analysts said demand data, U.S. crude inventories, the Iran conflict and the situation around the Strait of Hormuz are likely to remain key factors determining the direction of global oil prices in the coming days.
The latest decline should not necessarily be viewed as a sign of a sustained downward trend, as supply risks in the Middle East remain significant.
Pakistan’s inflation outlook will shape interest rates, household budgets, business costs and the rupee during FY2026-27.
Pakistan’s inflation rate has eased from earlier crisis levels, but the State Bank of Pakistan is warning that price pressures can rise again. For households and businesses, the key question is not whether one monthly number moves up or down. It is whether food, energy, taxes, the rupee and global commodity prices allow inflation to settle sustainably during FY2026-27.
Pakistan inflation outlook: the quick answer
SBP expects growth to improve but has signalled that inflation could move toward the upper end of its target range later in FY27. That means policy rates may decline only when the central bank is confident that the improvement is durable. A sharp rise in oil prices, administered energy tariffs, food shortages or rupee weakness could slow or reverse rate cuts.
Why inflation can rise after it appears under control
Base effects: year-on-year inflation can look low when compared with an unusually expensive month a year earlier, then rise as that comparison changes.
Energy prices: fuel, electricity and gas affect transport, manufacturing, agriculture and household bills.
Food supply: floods, heat, crop damage, storage problems and transport disruptions can push up essential prices quickly.
Exchange rate: a weaker rupee makes imported fuel, machinery, medicines and raw materials more expensive.
Taxes and administered prices: budget measures can lift prices even when private demand remains moderate.
What inflation means for interest rates
The policy rate influences the cost of borrowing across the economy. When SBP fears persistent inflation, it keeps rates higher to limit excess demand and support financial stability. When inflation expectations are anchored and external buffers are stronger, it has more room to reduce rates.
For consumers, lower rates can gradually reduce the cost of some loans. For businesses, they can make working capital and investment more affordable. The effect is not immediate, and banks price each borrower according to risk, collateral and market conditions.
Will the rupee strengthen?
The rupee depends on more than inflation. Export receipts, remittances, import demand, debt repayments, foreign investment and central-bank reserves all matter. A stable currency can reduce imported inflation, but an artificially fixed rate can create shortages and delayed adjustment. The healthier path is a credible market with adequate reserves and sustainable external financing.
What households should watch each month
Pakistan Bureau of Statistics consumer-price and weekly SPI releases.
Electricity fuel adjustments and quarterly tariff decisions.
Petrol and diesel price notifications.
Rupee-dollar movement and SBP reserve data.
Wheat, flour, vegetable, milk and transport prices in the local market.
How small businesses can prepare
Update cash-flow forecasts under more than one inflation and exchange-rate scenario. Negotiate shorter supplier-price validity periods, avoid excessive short-term debt and separate essential inventory from speculative stock. Where possible, improve energy efficiency and reduce imported inputs without compromising quality.
The bottom line
Pakistan has made progress toward macroeconomic stability, but inflation has not disappeared as a risk. The next phase will depend on disciplined fiscal policy, credible monetary policy, energy reform, food-supply resilience and export growth. Households should focus on the prices they actually pay, while investors should distinguish a temporary monthly change from a lasting shift in the trend.
Pakistan’s electricity tariff reflects energy costs, fixed capacity obligations, network expenses, taxes and periodic adjustments.
Pakistan’s electricity bill is not simply the price of the units a household consumes. It is the final result of several layers: the cost of producing energy, fixed payments to keep power plants available, transmission and distribution expenses, taxes, surcharges and periodic tariff adjustments. That is why a fall in fuel prices or lower electricity use does not always produce an equally large reduction in the monthly bill.
This Future Soch explainer separates those components and explains one of the most misunderstood terms in Pakistan’s power debate: capacity payments. It uses official material from the Ministry of Energy, NEPRA-linked tariff documents, the Finance Division and published circular-debt reports. Tariffs and adjustment amounts change over time, so readers should check their own bill and the latest regulator notifications for current rates.
First, what does an electricity bill pay for?
The Ministry of Energy’s consumer guidance says the basic energy charge begins with the number of kilowatt-hours used during the billing period multiplied by the applicable tariff. The final amount can also include taxes, fuel-price adjustments, quarterly tariff adjustments, financing charges and other approved items.
Energy charge: the variable cost associated with electricity consumed.
Capacity charge: fixed obligations connected to power plants being available to supply the system.
Network cost: transmission, distribution, metering and system-operation expenses.
Adjustments: changes linked to fuel costs, exchange rates, interest rates and earlier tariff calculations.
Taxes and surcharges: government levies and sector-financing charges shown on the bill.
What are capacity payments?
A power plant has costs even when it is not producing every minute. Investors must service debt, maintain equipment, employ technical staff, insure the facility and earn the return allowed under its contract. Capacity payments compensate eligible generators for keeping contracted capacity available to the national grid, subject to the relevant agreement and performance rules.
The simple distinction is this: an energy payment is linked to electricity actually generated, while a capacity payment is mainly linked to the ability to generate when the system calls for power. The exact formula varies by plant and tariff determination.
Capacity payments are not a separate line invented for a single household. They are part of the overall cost used to determine how much the power system must recover.
Why can bills stay high when demand is low?
Fixed costs do not disappear when national electricity demand falls. If the system has contracted more capacity than it regularly uses, those obligations are spread across fewer sold units. The fixed cost per unit can therefore rise. Seasonal demand makes the problem harder: Pakistan needs enough capacity for hot summer peaks, but demand falls sharply in cooler months.
High borrowing costs and a weaker rupee can also increase components that are indexed to interest rates or foreign currency. Fuel prices affect variable costs, but they are only one part of the total. Transmission constraints may prevent cheaper plants from supplying some areas, while distribution losses and weak bill recovery create additional financial pressure.
Where circular debt fits in
Circular debt is the accumulation of unpaid obligations across the power chain. When consumers or public bodies do not pay, distribution companies miss recovery targets, tariffs do not recover approved costs on time, or technical and commercial losses exceed allowed levels, the shortfall moves upstream. Generators, fuel suppliers and lenders then wait for payment.
The Finance Division’s published programme material put the stock of power-sector circular debt at about Rs2.53 trillion by February 2025. The Power Division continues to publish periodic circular-debt reports, including reports for 2026. The figure should not be confused with one year’s capacity payments: circular debt is a stock of accumulated unpaid obligations, while capacity payments are contracted power-purchase costs.
Do solar panels make the problem worse?
Rooftop solar reduces grid purchases for participating consumers and can cut fuel use during daylight hours. But if fixed system costs remain unchanged while more paying consumers buy fewer grid units, regulators must decide how those costs are shared. This is why net-metering rules, grid charges and buyback rates are debated so intensely.
The right conclusion is not that solar is the enemy. Pakistan needs cheaper local energy and cleaner generation. The policy challenge is to add solar without shifting an unfair share of network and legacy costs to households that cannot afford panels.
What reforms can reduce the burden?
Renegotiate or retire expensive obligations carefully. The Power Division says cancellation of 9,500 MW of unnecessary projects contributed estimated relief of about Rs1 per unit.
Sell more power productively. Higher industrial and commercial use can spread fixed costs across more units if it creates real output and does not require new subsidies.
Improve transmission. New lines and better system planning can allow lower-cost generation to reach demand centres.
Reduce theft and collection losses. Digital metering, feeder-level accountability and governance reform matter as much as headline tariff cuts.
Target subsidies. Support should reach vulnerable households directly instead of making every unit artificially cheap for all consumers.
Make contracts and tariff data easier to understand. Public, machine-readable disclosure would improve accountability and reduce misinformation.
What consumers should check on their bill
Compare current and previous meter readings, confirm the billing period, review the tariff category and look for fuel or quarterly adjustments. A sudden jump can come from higher consumption, a longer billing cycle, a change in protected-consumer status, an adjustment or an incorrect reading. Complaints should be filed through the relevant distribution company’s official channel, with photographs of the meter and bill retained as evidence.
The bottom line
Pakistan’s expensive electricity is not caused by a single contract or tax. It reflects a system that carries large fixed obligations, uneven demand, costly financing, network constraints, losses and accumulated arrears. Capacity payments are an important part of the equation, but solving the problem requires better planning, stronger distribution companies, transparent regulation and productive use of available power.
Future Soch view: the debate should move from slogans about one bill component to a public scorecard that shows fixed costs, energy costs, losses, recoveries and reform savings every month.
Pakistan’s digital economy has moved beyond the simple question of how many people are connected. The bigger test in 2026 is whether connectivity can produce better jobs, stronger businesses, safer payments and useful public services. Official data points to rapid scale: more than 150 million broadband connections, nearly 12 billion retail digital transactions in a year and a sharp improvement in international connectivity indicators. But scale alone will not guarantee productivity.
This Future Soch analysis brings together the latest available figures from the Pakistan Telecommunication Authority (PTA), State Bank of Pakistan (SBP) and Ministry of IT and Telecommunication. Figures refer to the reporting periods stated by each institution and should not be treated as real-time totals.
Pakistan’s digital economy in numbers
200 million-plus telecom subscribers and more than 150 million broadband connections, according to PTA’s 2024–25 annual report.
Telecom coverage exceeded 92%, while broadband penetration crossed 60%.
Retail digital transactions rose from about 6.9 billion to nearly 12 billion over one year, SBP reported in July 2026.
Active digital-payment merchants expanded from roughly 500,000 to more than 2 million.
Pakistan’s ICT Development Index score increased from 56.4 in 2025 to 67.7 in 2026, according to the Ministry of IT.
Connectivity has reached national scale
The country’s connectivity story is now measured in hundreds of millions. In its latest annual-report summary, PTA reported more than 200 million telecom subscribers and 150 million broadband connections. It also said telecom coverage exceeded 92% and broadband penetration moved above 60%.
The same report placed annual telecom-sector revenue above PKR 1 trillion, fiscal contributions at PKR 402 billion and sector investment at US$838 million. Data use reached 27,727 petabytes in 2025. These numbers show that digital connectivity is no longer a niche urban service; it is part of Pakistan’s national economic infrastructure.
Yet coverage maps can hide quality gaps. A person may technically live inside a covered area and still face weak signals, expensive devices, unreliable speeds or limited digital skills. The policy conversation therefore needs to move from basic access to meaningful connectivity: reliable networks, affordable smartphones, useful services and the ability to participate safely.
Digital payments are becoming economic infrastructure
Pakistan’s payment system is changing even faster than its media habits. In July 2026, the State Bank of Pakistan said retail digital transactions had increased from around 6.9 billion to nearly 12 billion over the previous year. Active merchants accepting digital payments grew from approximately half a million to more than 2 million, while mobile-banking app users reached nearly 137 million.
This matters because payments sit underneath e-commerce, freelancing, small-business growth, tax documentation and the everyday shift away from cash. Systems such as Raast can reduce transaction friction, but growth must be matched by cybersecurity, consumer protection and simple dispute-resolution mechanisms. A payment ecosystem earns trust slowly and can lose it quickly.
For businesses, the strategic opportunity is not only to add a QR code. Companies need mobile-first checkout, transparent pricing, clear delivery policies and customer support that works after payment. The winners will make the entire purchase journey trustworthy.
Digital inclusion is improving, but device access still matters
The expansion is also becoming more inclusive. Citing the GSMA Consumer Survey 2026, the Ministry of IT reported that women’s mobile-internet adoption increased to 53% in 2025 and the gender gap narrowed to 8%. Overall mobile-internet adoption reached 58% of the adult population.
That improvement is significant, but access is not always independent. The ministry noted that about 28% of women who use mobile internet rely on someone else’s device. Shared access can limit privacy, financial control, learning time and the ability to build an online business. Affordable smartphones, safety education and women-focused digital-skills programmes remain essential.
Pakistan is improving internationally
Pakistan’s international connectivity indicators also strengthened. The Ministry of IT said the country’s ICT Development Index score rose from 56.4 in 2025 to 67.7 in 2026. It reported a 22.8-point improvement in the connectivity pillar and a Meaningful Connectivity score of 79.
The trend is positive, but rankings should be treated as a diagnostic tool rather than a victory lap. The real benchmark is whether a student can learn without interruption, a freelancer can meet a deadline, a clinic can access records securely and a small seller can receive payment without confusion.
The next growth test: from consumption to productivity
Pakistan has already demonstrated mass adoption of video, social platforms, mobile apps and digital payments. The next phase must convert that attention into productive economic value. Five priorities stand out:
Affordable, reliable broadband: expand fibre, improve service quality and make devices easier to finance without trapping consumers in opaque terms.
Digital skills tied to income: training should connect to actual market demand in AI, software, cybersecurity, design, e-commerce and specialised services.
Cybersecurity and trust: stronger fraud prevention, privacy standards, platform accountability and public awareness are essential as more money moves online.
Digitisation of small businesses: merchants need practical tools for payments, inventory, logistics, customer data and compliant advertising—not merely social-media pages.
Better public data: regularly updated, machine-readable statistics would help investors, journalists and policymakers measure progress honestly.
What it means for media, brands and creators
For Pakistan’s media industry, a larger connected population creates reach but not automatic loyalty. Audiences increasingly expect fast video, credible explainers, searchable service journalism and transparent sourcing. Publishers that rely only on recycled headlines will struggle to build repeat visits or advertising value.
Brands should design campaigns for mobile screens, regional languages and measurable actions rather than vanity impressions. Creators need to diversify beyond platform algorithms through websites, newsletters, communities and direct commercial relationships. For more coverage, explore Future Soch’s Technology & Telecom, Business & Finance and Pakistan sections.
Outlook
Pakistan’s digital scale is real. Connectivity, payments and inclusion indicators are moving in the right direction. But the strongest economies are not built by subscriber totals alone. They are built when access becomes capability, capability becomes productivity and productivity creates trusted institutions, competitive businesses and better livelihoods.
Future Soch view: 2026 should be treated as the year Pakistan moves from celebrating digital access to measuring digital outcomes.